Home / Mortgages / Self-employed
Self-employed mortgages
You're not a risk. You're just harder to put in a box.
More people than ever work for themselves, and lenders still haven't caught up. If you've been turned down or given a figure that felt insultingly low, it usually isn't because you can't afford it. It's because the lender assessed your income the wrong way.
Book a free chatThe problem in one sentence
Two lenders can look at identical accounts and arrive at completely different figures, because they don't agree on what counts as your income.
Some use your salary plus dividends. Some use your share of net profit. Some average your last two years; some take the most recent year; a few will take the most recent year even if it's your best one. Some will lend on one year's accounts. Some want three.
That's the whole game: knowing which lender does which, and putting your case to that lender.
What we'll usually need to see
- Two years of accounts or SA302s and tax year overviews, if you have them
- One year is workable with the right lender
- Three to six months of business and personal bank statements
- If you're a limited company director, your accountant's figures including retained profit
- If you're contracting, your current contract and day rate
Don't worry if you're missing something. Tell us what you've got and we'll work from there.
Who this covers
Sole traders. Partnerships. Limited company directors. Contractors and day-rate workers. Freelancers. Anyone with a mix of employed and self-employed income.
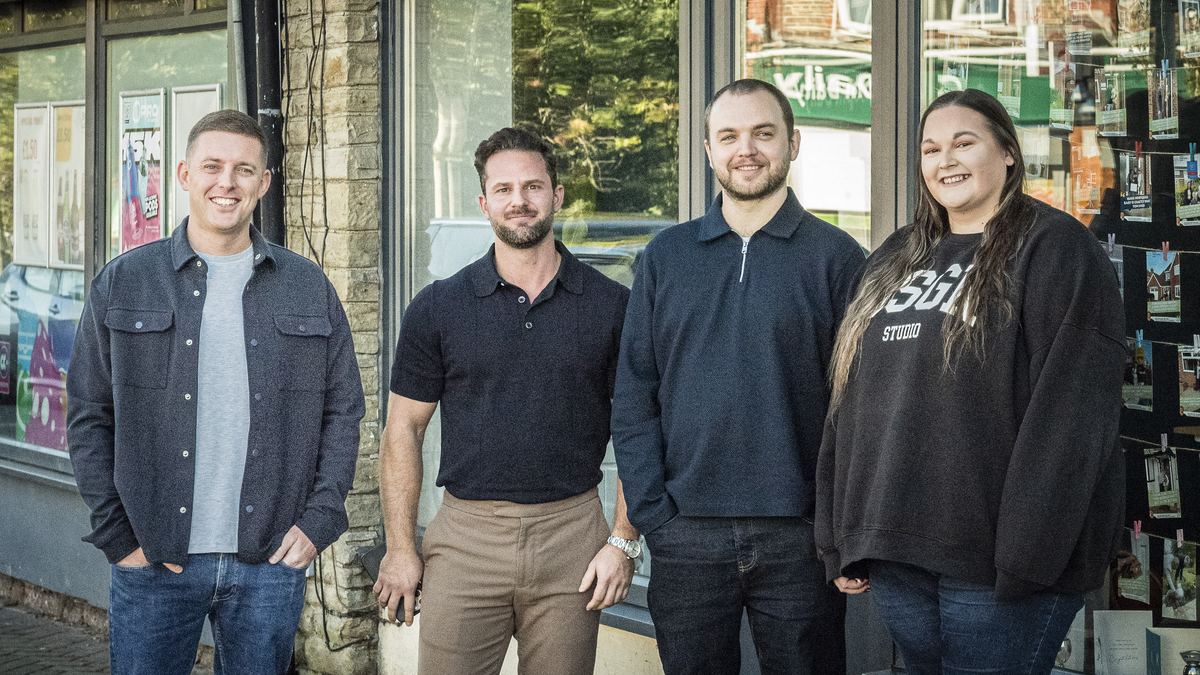
An accounting background, and years of contracting and self-employment. When your income comes from a day rate, or a set of accounts, or dividends plus retained profit, we're not seeing it for the first time.Why we're the ones to ask
An honest note
Being self-employed doesn't mean a mortgage is guaranteed, and any broker who tells you otherwise is selling you something. What it means is that the answer depends far more on which lender sees your file than it does on your accounts. That's the bit we can influence.
Your home may be repossessed if you do not keep up repayments on your mortgage or any other debt secured on it.
Not sure where you stand?
A first conversation costs nothing and commits you to nothing. Tell us what's going on and we'll tell you honestly what your options look like, including if the answer is "not yet".
Your home may be repossessed if you do not keep up repayments on your mortgage or any other debt secured on it.